I used to think retirement was something that happened to youlike a surprise party, except the party theme is “’80s knees”
and the cake is made of paperwork. Then one day I realized something mildly radical: I didn’t have to wait for a corporate
calendar invite labeled “Congratulations, you’re done!”
Retiring on my own terms meant choosing my exit with intention, not drifting into it because I was exhausted, burned out,
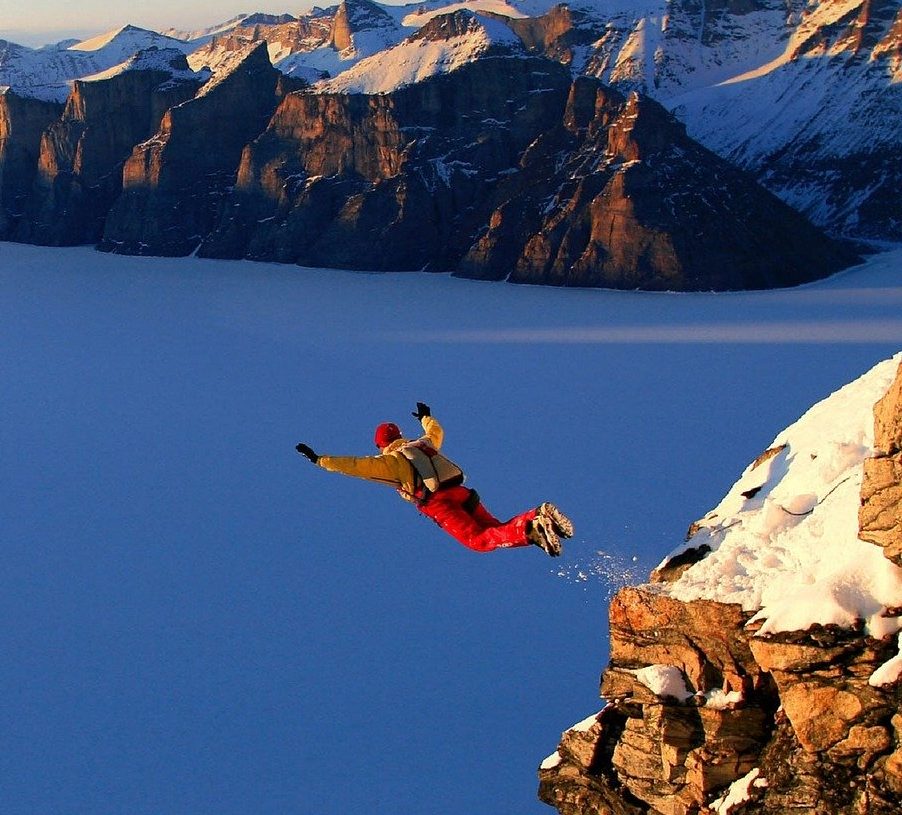
or one more “quick sync” away from fake-screaming into a pillow. But here’s the truth: a leap of faith is still a leap.
The goal is to pack a parachuteideally one that’s been tested, folded properly, and not purchased from a suspicious trunk
sale.
What “Retiring on My Own Terms” Actually Means (No, It’s Not Just Golf)
“My own terms” sounds cinematic, like I’m dramatically walking away from a desk while a slow clap builds behind me.
In real life, it’s more like: choosing a timeline, deciding what I’m retiring to, and making sure my money doesn’t
immediately start freelancing without my permission.
For some people, this looks like early retirement. For others, it’s semi-retirement: consulting, seasonal work, or a
passion project that pays enough to cover groceries and the streaming services you keep “meaning to cancel.” Either way,
the magic isn’t the date on the calendarit’s the control.
Step One: Define Your Retirement “Why” (Because Spreadsheets Don’t Hug You Back)
Money matters, but retirement is also a lifestyle switch. Before you even touch the numbers, ask:
- What do I want my average Tuesday to look like?
- What am I done with? (Commutes? Stress? Meetings that could’ve been emojis?)
- What am I moving toward? (Family time, volunteering, travel, learning, rest, building something)
This part sounds fluffy until you retire and realize you traded “busy” for “why am I reorganizing the pantry at 11:00 a.m.
on a Wednesday?” A strong “why” keeps the leap from turning into an identity crisis with a Costco receipt.
Step Two: Know Your Number (And Make It a Range, Not a Myth)
Retirement math gets overcomplicated fast. Start simple: estimate annual spending in retirement, then work backward.
Many people use a rough benchmark like saving about 25 times annual expenses as a starting point (often tied to
a 4% withdrawal concept). It’s not a promisejust a flashlight in the woods.
Here’s the key upgrade: don’t calculate a single number. Build a range:
- Lean plan: covers needs + a little joy
- Comfort plan: adds travel, hobbies, helping family
- “Life happens” plan: includes healthcare surprises, home repairs, helping adult kids, etc.
A retirement budget isn’t about deprivationit’s about clarity. And clarity is what lets a leap of faith feel less like a
free-fall.
Do a “Retirement Budget Dry Run”
One of the smartest moves is practicing living on your retirement budget before you retirelike a dress rehearsal,
except the costumes are sweatpants and realism. Try it for 3–6 months: route your “retirement income” to a separate
account and live off that. Anything extra goes straight to savings or debt payoff.
You’ll discover what’s truly essential, what’s negotiable, and what’s quietly been draining your wallet (hello, unused
subscriptions you “definitely need for motivation”).
Step Three: Build Your “Retirement Paycheck” (Because Bills Don’t Retire)
Retiring on your own terms works best when your income plan isn’t one giant guess. Think in layers:
- Guaranteed-ish income: Social Security, pensions, annuities (if used), part-time work
- Portfolio withdrawals: taxable brokerage, traditional IRA/401(k), Roth accounts
- Cash buffer: emergency fund + short-term spending cash
Why a Cash Buffer Can Save Your Sanity
Early retirement years can collide with market volatilityright when you’re withdrawing. That’s where
sequence-of-returns risk shows up: poor returns early in retirement can do more damage than poor returns
later, because withdrawals lock in losses.
One practical way to manage this is a “bucket” style approach: keep near-term spending money in cash or cash-like holdings,
mid-term funds in more stable investments, and long-term growth money invested for the future. It’s not the only method,
but it helps you avoid selling depressed assets just to pay the electric bill.
Step Four: Healthcare Is the Boss Level (Especially Before 65)
If you retire before Medicare eligibility, healthcare planning deserves its own tab, its own binder, and possibly its own
therapist. For many early retirees, the Health Insurance Marketplace can be a bridge, with potential savings based on
household income. Your income estimate mattersbecause it affects premium tax credits and out-of-pocket costs.
Practical options people often consider:
- COBRA (temporary extension of employer coverageoften pricey, sometimes worth it for continuity)
- Marketplace plans (income-based subsidies may apply depending on your situation)
- Spouse/partner plan (if available)
- Part-time work with benefits (the “semi-retirement with dental” strategy)
Medicare Timing: Don’t Miss the Window
Medicare has enrollment rules and penalties that are famously unforgiving. Generally, your initial enrollment period is a
7-month window around turning 65. And if you delay Part B without a qualifying reason, you can face a late-enrollment
penalty that increases your premium (often calculated per 12-month period of delay).
Translation: put Medicare dates on your calendar like they’re Taylor Swift tickets.
Step Five: Social SecurityThe Lever You Can Pull (If You Understand It)
Social Security planning is one of the biggest “retire on your own terms” power moves, because it’s flexible. Claiming
earlier can provide cash flow and reduce portfolio withdrawals; delaying can increase your monthly benefit. If you delay
past full retirement age, you earn delayed retirement credits up to age 70, which can meaningfully boost your check.
There isn’t one perfect claiming age. But there is a smart way to decide:
- Health and longevity: family history, personal health, and realistic expectations
- Portfolio risk: using Social Security as a “floor” can reduce withdrawal pressure
- Spousal strategy: higher earner delaying may boost survivor benefits
- Work plans: earnings rules can apply if you claim before full retirement age and keep working
Don’t Forget Taxes on Social Security
Social Security benefits can be taxable depending on your “combined income.” The headline is simple: up to 85% of benefits
may be taxable at certain income levels. The real-world implication is even simpler: your withdrawal strategy affects your
tax bill, and your tax bill affects how long your money lasts.
Step Six: Tax Planning Isn’t Optional (It’s the Silent Budget Line Item)
In working life, taxes get taken out automatically and you mostly ignore it. In retirement, taxes become a strategy game.
Withdraw from the wrong bucket at the wrong time, and you can trigger higher taxes, Medicare premium surcharges for higher
incomes, or both.
Many retirees explore a tax-aware withdrawal orderoften drawing from taxable accounts first, then tax-deferred accounts,
and leaving Roth accounts for later. That’s not a universal rule, but it’s a common starting framework because it may help
keep some assets growing tax-advantaged longer and offer flexibility later.
RMDs: The Deadline You Don’t Want to Forget
Required Minimum Distributions (RMDs) are mandatory withdrawals from certain retirement accounts once you hit the required
age. The IRS rules include penalties if you miss or under-withdraw. The penalty can be substantial (and may be reduced if
corrected within a specified time window), so this is the kind of thing you automate or review annuallypreferably before
December turns into chaos.
Step Seven: The “Leap of Faith” Plan That Isn’t Reckless
This is where the emotional and practical sides finally shake hands.
If you’re going to retire on your own terms, create a pre-leap checklist:
1) Build a Runway (12–24 Months if You Can)
A runway is cash and low-volatility money set aside so you’re not forced to sell investments during a bad market year.
It’s also a confidence booster. When you can pay bills without panic, retirement feels like freedomnot a financial stunt.
2) Stress-Test Your Plan
Ask “what if” questions, then answer them with actual numbers:
- What if the market drops 20% in year one?
- What if we need a new roof and a new knee in the same year?
- What if inflation stays elevated longer than expected?
- What if one of us needs long-term care support?
You don’t need to predict the futureyou need a plan that can flex without breaking.
3) Design a “Work Optional” Off-Ramp
Retiring on your own terms doesn’t have to be all-or-nothing. Many people choose a glide path:
consulting, freelancing, seasonal work, or a passion business that covers discretionary spending.
The trick is setting boundaries so “a little work” doesn’t quietly become “my old job, but with fewer benefits.”
4) Build Your Retirement Life Like You Built Your Career
Careers give structure: milestones, feedback, community, purpose. Retirement removes that overnight.
Replace it on purposeclubs, classes, volunteering, fitness routines, creative projects, mentoring, community groups.
You’re not just retiring from work. You’re building a life you actually want to wake up to.
Common Mistakes People Make (So You Can Avoid Them Like a Pro)
Underestimating Healthcare Costs
Healthcare isn’t just premiumsit’s deductibles, prescriptions, dental/vision/hearing, and the unexpected. Plan with a
buffer. Your future self will thank you (and possibly stop side-eyeing you from the mirror).
Ignoring Sequence-of-Returns Risk
Retiring into a down market without a buffer can force bad decisions. A cash runway, flexible spending, and a
thoughtful withdrawal plan can reduce pressure when markets are ugly.
Forgetting That “Spending” Changes Over Time
Retirement spending often shifts: travel-heavy early years, steadier middle years, and potentially higher healthcare
costs later. Build a plan that acknowledges phasesnot a flat line.
Not Practicing the Retirement Budget
If you’ve never lived on your projected retirement income, retirement day can feel like stepping into a dark room and
hoping the furniture moved out. Do the dry run.
So…Was It Worth It?
Retiring on my own terms wasn’t one brave moment. It was a series of practical decisions that made the brave moment
possible. The leap of faith was realbut it wasn’t blind. It was backed by a budget, a healthcare plan, a tax strategy,
and an honest look at what I wanted the next chapter to feel like.
And yes, some days I still miss the paycheck rhythm. Then I remember: I also don’t miss the calendar alerts that used to
pop up like jump scares.
Extra : Experiences From the Other Side of the Leap
Here’s the part I didn’t fully appreciate until I actually did it: retiring “on my own terms” isn’t a single finish line.
It’s a transition. And transitions are messy. They come with surprise emotions, weirdly specific worries, and an odd
amount of time to notice how loud your refrigerator is.
The first month felt like an extended weekendglorious and slightly suspicious. I caught myself checking email the way
you check your pocket for your phone when it’s already in your hand. My brain was still trained to look for urgency,
even though the only urgent thing in my day was figuring out why the lawn suddenly looked like it had opinions.
By month two, I learned the difference between rest and recovery. Rest is taking a day off.
Recovery is realizing you’ve been running hot for years and your nervous system needs time to cool down. I slept more.
I laughed more. I also had moments of “Who am I if I’m not productive?” which is a rude question to receive from your own
brain at 2:00 a.m.
Money-wise, the dry run saved me. I discovered I had been casually spending like I had a magic replenishing salary fairy.
Retirement spending is different because every purchase feels a little more intentional. Not scaryjust more aware.
I started thinking in trade-offs: “Do I want this upgrade, or do I want three more long weekends this year?”
Weirdly, that made spending feel better, not worse. I wasn’t deprivedI was choosing.
Healthcare planning was the most “adulting” part of the whole process. I became the kind of person who reads plan details.
The kind of person who says things like “network coverage” without irony. Past Me would be horrified.
Present Me is simply grateful I don’t have to learn these lessons in a panic.
The biggest surprise? Community. Work gives you built-in people. Retirement requires you to build your own.
I started saying yes to things I used to ignore: a morning walking group, volunteering, lunch with friends on a Tuesday
(scandalous), even classes that were purely for fun. And slowly, my days gained a new rhythmless frantic, more human.
If you’re considering the leap, here’s my honest takeaway: you don’t need to be fearless.
You need to be prepared enough that your fear doesn’t get to drive. When you’ve done the workbudget, runway, healthcare,
income planthe leap stops being reckless and starts being brave in the best way.